5th Pay Commission Pay Fixation Formula
The 5th Pay Commission Pay Fixation Formula is critical to understanding how the pay of Central Government employees was revised under the 5th Central Pay Commission (5th CPC). The revised pay structure was carried out via the Central Civil Services (Revised Pay) Rules, 1997, with effect from January 1, 1996, issued with the relevant guidelines and alternatives exercised by way of employees.
Unlike the later 7th Pay Commission, which delivered a Pay Matrix and a uniform 2.57 multiplication issue, the 5th Pay Commission used an exclusive approach. Under the CCS (Revised Pay) Rules, 1997, 40% of the simple pay in the present scale was added to the existing emoluments, and the resulting amount was then used to determine the right level in the revised pay scale.
This article explains the 5th Pay Commission pay fixation method, its calculation method, vital situations, examples, and the distinction between the fifth CPC components and later pay commissions.
What Was the 5th Pay Commission?
The 5th Central Pay Commission was constituted to take a look at and propose modifications within the pay structure, allowances, service conditions, and related subjects of Central Government personnel.
Its recommendations ended in revised pay scales that were implemented through the Central Civil Services (Revised Pay) Rules, 1997. The Department of Expenditure continues to maintain the legitimate archive of Central Government pay-associated regulations and orders, which includes the 1997 revised pay guidelines.
The 5th CPC revision become associated with the duration beginning January 1, 1996. The revised policies furnished specific strategies for fixing the pay of employees who moved from the prevailing scales to the revised scales.
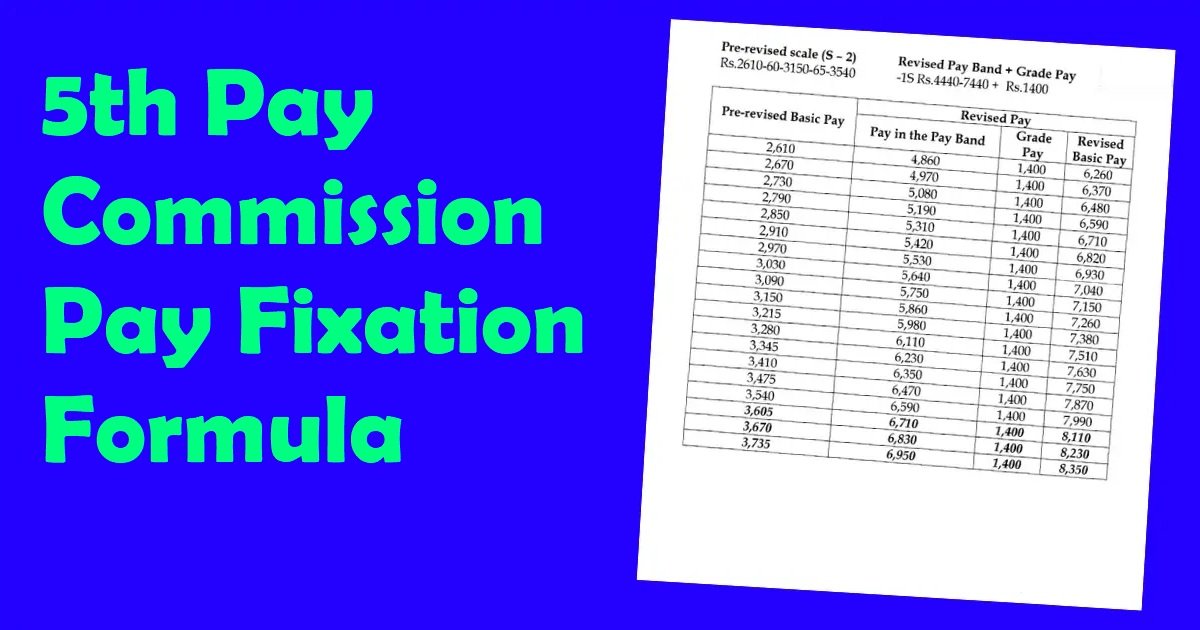
5th Pay Commission Pay Fixation Formula
The primary components under Rule 7 of the CCS (Revised Pay) Rules, 1997 may be explained as follows:
Revised fixation quantity = Existing emoluments + 40% of current fundamental pay
After calculating this amount, the employee’s pay was fixed on the level next above the quantity calculated in the applicable revised pay scale.
In simplified terms:
1: Determine the prevailing fundamental pay.
2: Calculate 40% of the present basic pay.
3: Add this 40% amount to the present emoluments.
4: Find the next higher stage within the relevant revised pay scale.
5: Fix the employee’s revised fundamental pay at that level, subject to the minimum and maximum provisions of the revised scale.
The actual rule is more precise than simply multiplying basic pay by 1. 40 because the term “present emoluments” has a specific meaning under the regulations.
5th CPC Pay Fixation Formula Table
| Particular | 5th Pay Commission Treatment |
|---|---|
| Effective revision period | From January 1, 1996, subject to applicable rules |
| Main rules | CCS (Revised Pay) Rules, 1997 |
| Additional percentage | 40% of existing basic pay |
| Base for 40% calculation | Existing basic pay |
| Existing emoluments | Defined under the applicable rules |
| Final fixation | Next higher stage in revised scale |
| Minimum of revised scale | Pay fixed at minimum if calculated amount was below it |
| Maximum of revised scale | Pay fixed at maximum if calculated amount exceeded it |
| Bunching | Special provisions applied |
| Pay scale method | Revised pay scales, not the later 7th CPC Pay Matrix |
What Does 40% Fitment Mean within the fifth CPC?
The phrase 40% fitment is commonly used whilst discussing the 5th Pay Commission. However, it is vital to understand what it in reality means.
It does not suggest that an employee ought to clearly calculate:
Basic Pay × 1.40 = Final Revised Basic Pay
in every case.
The rule stated that a quantity representing 40% of the primary pay in the existing scale is added to the employee’s existing emoluments. The resulting amount was then used for fixing pay at the next stage within the revised scale.
Therefore, the 40% factor becomes an important part of the fixation process; however, the final revised simple pay is based on the relevant revised scale and its levels.
What Were “Existing Emoluments”?
This is one of the most essential factors when understanding the 5th pay fixation method.
Under the policies, “current emoluments” had no longer been limited to the worker’s basic pay. The definition covered detailed components.
For the general fixation provision, the present emoluments included the fundamental pay, the applicable Dearness Allowance, and the specified first and 2nd instalments of meantime comfort admissible under the relevant orders.
This is why a historic 5th CPC pay fixation calculation should not be performed robotically by multiplying the old basic pay by 1.40 and calling the result the revised basic pay.
Simple Example of 5th Pay Commission Pay Fixation
Suppose, simply as an instance, an employee had a current basic pay of:
₹5,000
The 40% factor could be:
40% of ₹5,000 = ₹2,000
The calculation would therefore include a further ₹2,000 as the 40% factor.
However, the quantity used for fixation might additionally depend on the relevant definition of existing emoluments under the regulations. Therefore, if the worker’s eligible existing emoluments had been ₹X, the calculation would conceptually be:
₹X + ₹2,000
The ensuing difference could then be compared with the degrees of the relevant revised pay scale. The worker’s pay could generally be constant on the stage subsequent above the amount so computed, subject to the minimum and maximum provisions.
This example demonstrates the method rather than supplying a widespread income conversion due to the fact the real calculation relies upon the worker’s existing scale, basic pay, applicable allowances, intervening time relief, and the relevant revised scale.
Minimum Pay Rule
The fifth CPC regulations additionally contained a crucial minimum-pay provision.
If the quantity calculated below the fixation method came out to much less than the minimum of the revised scale, the worker’s pay was constant on the minimum of that revised scale.
For example, if the calculated amount became ₹6,200 but the minimum of the relevant revised scale turned into ₹6,500, the fixation might be at ₹6,500 in place of ₹6,200.
This provision ensured that the calculated amount did no longer result in pay below the minimum of the relevant revised scale.
Maximum Pay Rule
The rules also dealt with situations wherein the calculated amount became above the maximum of the revised scale.
If the amount arrived at via the fixation procedure turned out to be more than the maximum of the revised scale, pay was fixed at the maximum of that scale, subject to the applicable provisions.
Therefore, the method became not a limitless percentage growth. The revised scale itself established obstacles within which pay became usually fixed.
Bunching of Pay Under 5th CPC
Another important characteristic of the 5th CPC fixation regulations turned into the remedy of bunching.
Bunching may arise when employees drawing pay at numerous consecutive degrees in an existing scale were placed at the same level in the revised scale.
The regulations supplied additional increments in targeted instances where more than 4 consecutive stages have become bunched. Broadly, employees in the 5th via 8th degrees ought to receive one increment; those in the 9th via 12th degrees may want to get hold of two increments wherein the applicable bunching persisted beyond the 8th level; and those in the thirteenth through sixteenth degrees could receive 3 increments where bunching persisted past the 12th degree.
These provisions have been designed to cope with the compression that could otherwise occur during conversion from the antique scales to the revised scales.
One Increment for Every Three Existing Increments
The rules additionally contained a protection regarding increments.
The fixation provisions have been intended to make sure that an employee would get hold of at least one increment inside the revised scale for every three increments, inclusive of stagnation increments wherein applicable, in the current scale, problem to the exact situations of the guidelines.
This is a critical reason why ancient pay fixation cannot usually be reconstructed by the use of a simple percentage calculation.
5th Pay Commission Pay Fixation After January 1, 1996
The policies additionally provided for situations in which a worker preferred to attract pay within the existing scale and moved to the revised scale from a date later than January 1, 1996.
Rule 9 handled fixation within the revised scale after January 1, 1996. The present pay at the later date was considered under the relevant provisions for figuring out fixation.
Therefore, the date from which an employee moved to the revised scale will be crucial in figuring out the real fixation.
5th CPC Pay Fixation and Special Pay
The policies also contained separate provisions for employees who received special pay or non-training allowance (NPA) and for different classes.
In such instances, the definition of current emoluments and the treatment of special pay or NPA should differ from the normal fixation technique. For example, the policies targeted a separate remedy for clinical officers receiving NPA.
Therefore, an employee’s designation, allowances, and service conditions could have an effect on the precise calculation.
Difference Between 5th CPC and 7th CPC Pay Fixation
The 5th and 7th Pay Commissions use fundamentally different tactics.
Under the 5th CPC, the fixation mechanism covered the addition of 40% of existing basic pay to current emoluments and fixation at the following stage of the revised scale.
Under the seventh CPC, the authorities added a Pay Matrix. Rule 7 of the CCS (Revised Pay) Rules, 2016 provided for multiplying existing pay by a 2.57 fitment component and setting the result in the best Pay Matrix stage in step with the relevant guidelines.
rules.
| Feature | 5th CPC | 7th CPC |
|---|---|---|
| Main revision rules | CCS (RP) Rules, 1997 | CCS (RP) Rules, 2016 |
| Pay structure | Revised pay scales | Pay Matrix |
| Main fixation mechanism | 40% added to existing emoluments | Existing pay multiplied by 2.57 |
| Stage-based fixation | Yes | Pay Matrix cell selection |
| Pay Matrix | No | Yes |
| Effective revision date | January 1, 1996 | January 1, 2016 |
The 2.57 thing needs to no longer be applied to 5th CPC calculations. It belongs to the seventh CPC pay-fixation framework. The Department of Expenditure itself distinguishes the 7th CPC fitment aspect from other standards used inside the Pay Matrix.
Is the 5th Pay Commission Formula Still Used for Current Salary Calculation?
For most current Central Government employees, the 5th CPC fixation formula is an ancient pay-revision system, not the ordinary method for calculating contemporary primary pay.
The 6th and 7th Central Pay Commissions ultimately introduced one-of-a-kind pay structures. The 7th CPC Pay Matrix is the modern-day framework for personnel governed by the CCS (Revised Pay) Rules, 2016.
However, the 5th CPC method can nevertheless be applicable whilst analyzing old service facts, historical pay fixation, pension-associated records, arrears, court docket cases, or personnel who persevered below older pay-scale arrangements.
The Department of Expenditure maintains archival records regarding personnel drawing pay below the 5th CPC scales, together with orders relating to Dearness Allowance.
How to Calculate 5th CPC Pay Fixation Correctly
For an ancient calculation, follow these steps:
- Identify the worker’s existing simple pay.
- Identify the relevant present pay scale.
- Calculate 40% of the present basic pay.
- Determine the relevant current emoluments under the 1997 policies.
- Add the 40% increase to the present emoluments.
- Identify the corresponding revised pay scale.
- Find the following higher degree above the calculated amount.
- Apply the minimum and maximum provisions.
- Check whether bunching provisions apply.
- Check the employee’s increment role and any unique provisions.
This procedure is a whole lot more dependable than using a general online percentage calculator.
Important Points About the FifthPay Commission Formula
| Point | Explanation |
|---|---|
| 40% component | 40% of existing basic pay was added to existing emoluments |
| Existing emoluments | Had a specific definition under the rules |
| Final fixation | Generally at the next stage above the calculated amount |
| Minimum scale | Minimum applied when the calculated amount was below it |
| Maximum scale | Maximum applied when the calculated amount exceeded it |
| Bunching | Special increment provisions could apply |
| Increment protection | Rules included provisions relating to existing increments |
| Effective date | January 1, 1996 was the principal commencement date |
| Later fixation | Rule 9 addressed movement to revised scales after January 1, 1996 |
| 7th CPC factor | 2.57 belongs to the 7th CPC, not the 5th CPC |
5th Pay Commission Pay Fixation Formula: Key Takeaway
The 5th Pay Commission Pay Fixation Formula became primarily based on the Central Civil Services (Revised Pay) Rules, 1997. The imperative mechanism changed to add an amount equal to 40% of the employee’s current basic pay to the employee’s described current emoluments and then restore the pay to the next higher degree in the applicable revised pay scale. Minimum and maximum limits, bunching provisions, increment safety, and special categories also need to be taken into consideration.
The most essential point is that 40% should now not be treated as a standalone multiplication factor for every employee. The policies used the idea of existing emoluments and required the ensuing quantity to be fitted into the correct revised scale.
For historic salary verification, the worker’s old simple pay, pay scale, date of fixation, applicable allowances, meantime comfort, revised scale and service situations ought to all be checked against the applicable policies and orders.
Frequently Asked Questions
What turned into the 5th Pay Commission pay fixation system?
Under the overall Rule 7 process of the CCS (Revised Pay) Rules, 1997, 40% of existing simple pay was added to existing emoluments, after which pay was fixed at the next better stage in the revised scale, subject to the relevant minimum and maximum provisions.
Was the 5th CPC fitment issue 1.40?
The guidelines used a 40% addition to primary pay, but calling 1.40 as a common, very last pay-fixation multiplier may be misleading due to the fact that the calculation additionally concerned the described present emoluments and degree fixation within the revised pay scale.
What became the effective date of the 5th Pay Commission revision?
The CCS (Revised Pay) Rules, 1997 furnished for revised pay structures associated with January 1, 1996, challenge to the applicable provisions and character alternatives.
Did the 5th CPC have a Pay Matrix?
No. The 5th CPC used revised pay scales and ranges. The Pay Matrix is associated with the 7th CPC.
Is the 2.57 aspect part of the 5th Pay Commission?
No. The 2.57 fitment issue belongs to the seventh CPC pay-fixation machine beneath the CCS (Revised Pay) Rules, 2016.
Why is the 5th CPC calculation exclusive of a simple forty% bump?
Because the policies required the 40% aspect to be added to defined existing emoluments, after which required fixation at a level within the revised pay scale. Other provisions, including bunching and increment-related provisions, may also affect the final result.
Where can the professional 5th CPC guidelines be checked?
The Department of Expenditure maintains the legitimate Central Government archive of pay-associated policies and files, including the CCS (Revised Pay) Rules, 1997.